The page you were trying to view is not available for your role.
Summary
Recent attacks affecting a major energy-producing region illustrate why geopolitical headlines do not translate automatically into predictable market outcomes. The latest commentary from Ian Jensen-Humphreys argues that investors are better served by assessing probabilities and maintaining resilient long-term plans, than by making confident short-term forecasts.
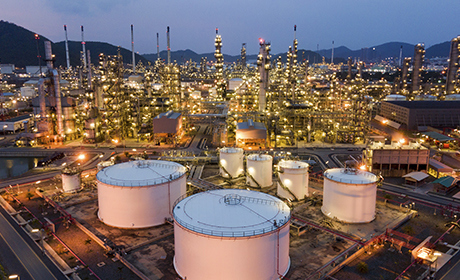
Cast your mind back to the weekend. As advisers were enjoying a well-earned break, markets were handed another reminder that geopolitics has an unfortunate habit of ignoring the calendar.
Houthi attacks on Saudi Arabia, including a deadly strike on Riyadh's King Khalid International Airport, immediately rekindled concerns about regional stability and the security of energy infrastructure. Further attacks were reported on Sunday, adding to fears that tensions could escalate further.
For investors, the instinctive response is familiar. Bad news in a major oil-producing region must surely mean higher oil prices, higher inflation and lower markets.
If only it were that simple.
One of the great frustrations of investing is that markets rarely read the script we've written for them. That's particularly true when geopolitics enters the picture.
The Chain
Investors love connecting dots -
- Middle East tensions lead to higher oil prices.
- Higher oil prices lead to inflation.
- Inflation leads to higher interest rates.
- Higher interest rates lead to weaker economic growth.
It's a perfectly logical sequence. In fact, it's so logical that investors often assume it will happen automatically. The trouble is that markets don't react to headlines. They react to expectations. And expectations can be remarkably difficult to predict.
The weekend's events have undoubtedly increased uncertainty around global energy markets and shipping routes. Analysts have highlighted concerns around the strategic importance of regional transport corridors and their implications for oil flows.
The challenge is that every link in the chain contains assumptions -
- Will energy supplies actually be disrupted?
- Will spare production capacity offset any shortages?
- Will governments release strategic reserves?
- Will consumers and businesses continue spending as normal?
The answers matter far more than the headlines themselves. Investors aren't trying to work out what happened yesterday – they're trying to work out what happens next. As every adviser knows, that's considerably more difficult.
Little Lies
One of the most dangerous phrases in investing is "this time it's obvious". When uncertainty rises, commentators often become strangely certain -
- Oil prices are definitely going higher.
- Inflation is definitely returning.
- Markets are definitely doomed.
Experience suggests otherwise.
History is full of confident forecasts that looked compelling over a weekend and ridiculous six months later. That's not because investors are unintelligent – it's because the world is complex.
The reality is that nobody knows with certainty how geopolitical events will evolve. Markets are constantly weighing probabilities rather than certainties, even if financial television occasionally gives the impression that everyone knows exactly what's about to happen next.
They don't.
And that's perfectly normal.
Go Your Own Way
The most interesting market moves are often the ones that don't happen.
Think back over the past decade. There have been plenty of occasions where investors expected a geopolitical event to trigger a lasting market sell-off. Instead, markets dusted themselves down and moved on remarkably quickly.
That's because long-term returns are often driven by factors that receive far less attention than dramatic headlines -
- Corporate earnings.
- Productivity growth.
- Innovation.
- Consumer spending.
The market has an annoying tendency to focus on what will matter over the next five years rather than what dominated the front page over the last five hours. This doesn't mean geopolitical events are unimportant – it simply means that investors should be cautious about assuming that today's headline automatically becomes tomorrow's investment outcome.
Don't Stop
As advisers, there is perhaps a broader lesson worth sharing with clients this week.
Uncertainty is not an occasional feature of investing.
It is the default setting.
There's always something.
- A war.
- An election.
- A referendum.
- An inflation scare.
- A banking crisis.
- A geopolitical shock.
Or, in this week's case, attacks on key infrastructure in one of the world's most important energy-producing regions.
The specific concern changes. The feeling doesn't. That's precisely why diversified portfolios exist – not because we can predict every risk, but because we know we can't.
The temptation after every major news event is to hunt for a crystal ball. To find someone who can confidently explain exactly where oil prices, inflation and markets are heading next. Sadly, that person remains stubbornly unavailable.
Instead, investors are left with something less exciting but considerably more useful: diversification, discipline and patience.
It may not make for a Hollywood blockbuster. But history suggests it's still one of the best investment strategies around. And if Fleetwood Mac taught us anything, it's that markets, like relationships, are complicated, emotional and occasionally irrational.
The trick isn't predicting every twist and turn – it’s making sure your plan survives them.
Key takeaways
- Markets don’t always follow the headlines
Geopolitical events can increase uncertainty, but their impact on oil, inflation and markets is rarely as predictable as it first appears. - Think in probabilities, not certainties
Markets react to expectations about what happens next, so confident short-term forecasts can quickly prove wrong. - Focus on resilience, not prediction
Diversification, discipline and patience can help investors navigate uncertainty without trying to predict every twist and turn.
Ian Jensen-Humphreys
Portfolio ManagerIan is a portfolio manager of the Quilter Investors Cirilium and Creation Portfolios. Ian joined Quilter Investors in March 2020 from Seven Investment Management (7IM), where he was deputy chief investment officer. Ian also spent 15 years at Goldman Sachs in risk management and portfolio hedging strategies.
Ian is a CFA charterholder and has a degree in Physics from the University of Oxford.