The page you were trying to view is not available for your role.
Investment decisions are rarely driven by logic alone. Behavioural science shows that emotions, mental shortcuts, and social influences often play a far greater role than spreadsheets or projections. Understanding these behavioural forces is essential to helping your clients make better long-term decisions.
At the centre of this is cognitive dissonance. This is the discomfort created when two conflicting beliefs exist at the same time. To ease that discomfort, people often change their behaviour, not in the most rational way, but in the way that feels the emotionally easiest.
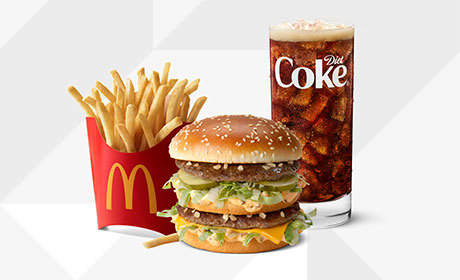
Can I take your order?
Have you ever been to McDonalds and ordered a diet coke with your meal? If you did, you are not alone, about a third of people will choose a diet coke over a regular coke with their meal.
This is an example of cognitive dissonance. Rationally, the impact is marginal. Emotionally, however, it allows people to tell themselves a reassuring story: ‘at least I made a healthier choice’. The behaviour hasn’t changed, but the discomfort has eased.
The same pattern appears repeatedly in investing.
Fear versus necessity
The decision to invest at all is often shaped by two competing ideas. On one side sits the rational understanding that investing is necessary to protect wealth against inflation. On the other sits a very human fear of market falls and losing money.
When these ideas clash, many people default to inaction. Not investing becomes the easiest way to resolve the tension. Negative market headlines then help justify that decision: ‘I’m glad I stayed out – look what happened’.
This is reinforced by social norms. In the UK, fewer than a quarter of people invest outside their pension. Holding cash feels safe because it is common, even though large sums are slowly losing value in real terms. People follow the crowd, assuming that if everyone else is doing it, it must be the right thing to do.
Negativity bias and the news cycle
Even when clients do invest, they are not operating in a neutral environment. Negativity bias means losses feel around twice as painful as gains feel pleasurable. As a result, negative information grabs attention and provokes stronger emotional reactions.
Media coverage amplifies this bias. Headlines frequently focus on money being ‘wiped off’ stock markets, even during periods when markets rise overall. Over time, this creates a distorted perception of risk, increasing anxiety, and reinforcing pessimistic behaviour.
Framing matters more than we think
How investment decisions are framed can also influence outcomes. Regulated investment advice requires multiple warnings about areas like risk and past performance. Meanwhile, holding cash in an account returning less than inflation (which many do) carries no equivalent warnings, despite representing ongoing, real harm.
This imbalance can unintentionally push clients towards decisions that feel safer but are worse in the long run.
The cost of constant monitoring
Meanwhile, our 24/7 world and the availability of digital platforms make it easier than ever for clients to frequently monitor investments. While access and transparency have benefits, daily checking can increase anxiety and lead to myopic loss aversion – a focus on short‑term losses at the expense of long‑term outcomes.
Markets fall on a significant number of days, and because losses feel so uncomfortable, clients can develop a strong urge to act, often selling at precisely the wrong time. Behaviour, not market fundamentals, becomes the driver of poorer outcomes.
Decumulation and emotional risk
If we look at investing in retirement, cognitive dissonance does not disappear, it intensifies. Your clients need income, but fear risk. The desire for certainty can lead many to hold a substantial ’cash buffer’, but holding too much cash increases inflation risk and longevity risk.
This decumulation dilemma can lead to overly cautious decisions that feel reassuring in the short term but increase the risk of running out of money later.
Your real value
Ultimately, financial advice is as much about managing behaviour as managing portfolios. You play a crucial role in helping your clients navigate cognitive dissonance, negativity bias, and herd behaviour through education, planning, and ongoing reviews.
For some investors, solutions that reduce day‑to‑day volatility and emotional noise can support this process, making it easier to stay invested and focused on long‑term outcomes.
A smoother journey
Whether your clients are approaching retirement or already enjoying it, the Quilter Smoothed Funds have been built to give them a more reliable and reassuring way to invest.
Built in partnership with Standard Life, the Quilter Smoothed Funds are designed to deliver a more stable investment experience to your clients by reducing the size of the day-to-day fluctuations to their fund value.
By using a rolling-average smoothing process that is straightforward and easily explained, the Quilter Smoothed Funds can offer you and your clients a simpler, steadier, and smoother way to invest.
Find out about Quilter Smoothed Funds
Find out how the Quilter Smoothed Funds could give your clients the confidence to stay invested and enjoy a more sustainable income in retirement.