
The page you were trying to view is not available for your role.
Advisers often focus tax planning on wrappers and investments, but cash can play just as important a role – particularly when allowances are considered across a household.
For couples where one spouse is a higher earner and the other has little or no taxable income, cash planning can unlock a surprisingly large amount of tax‑free income.
Here’s how the allowances work in practice:
A low‑earning spouse (with income below £12,570, tapering up to £17,570) benefits from a £5,000 Starting Rate for Savings.
Separately, as long as they remain a basic‑rate taxpayer, they also have a £1,000 Personal Savings Allowance. This applies regardless of whether their Personal Allowance is fully used
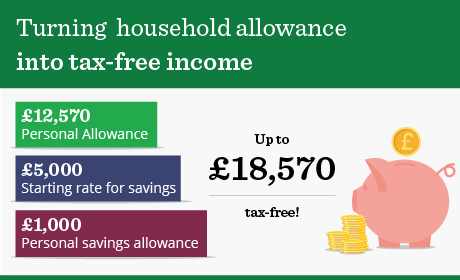
Where the low‑earning spouse has little or no taxable income, these can potentially be combined with the £12,570 Personal Allowance, allowing for:
- £12,570 Personal Allowance
- £5,000 Starting Rate for Savings
- £1,000 Personal Savings Allowance
That’s up to £18,570 of income and interest tax free.
What does this mean in real terms?
At a 4% interest rate, transferring £125,000 of cash from a higher‑earning spouse into the lower‑earning spouse’s name could generate £5,000 of interest tax free.
If the lower earning spouse is already using their £12,570 Personal Allowance, this continues to be an attractive option. A £150,000 cash balance earning 4% could generate £6,000 of interest, still within their available savings allowances.
And where that £12,570 income is taken from a pension – for example, from a CRA‑taxed pot alongside £4,190 from tax‑free cash – this creates a potential £22,760 of total tax‑free income.
Source: Tax on savings interest: How much tax you pay - GOV.UK
Where CashHub adds real value
This is where CashHub becomes a powerful planning tool.
By using CashHub, advisers can:
- Help clients hold larger cash balances efficiently
- Keep cash visible alongside investments
- Make it easier to use household allowances strategically
- Demonstrate clear, tangible value beyond investment selection
Rather than cash sitting in the background, CashHub allows it to become an active part of your clients’ tax planning – and a clear benefit of ongoing advice.
Further support
If you’d like to explore how CashHub can support these conversations with your clients, speak to your Quilter Platform contact or visit the CashHub adviser pages.